


Key takeaways
- Break-even = closing costs ÷ monthly payment savings.
- A lower payment can still mean more total interest if the new term is longer.
- Cash-out refinancing increases the loan and is not free money.
- Compare the Loan Estimate, not a verbal quote.
- If you may move soon, a long break-even is a real risk.
What a refinance actually does
Refinancing replaces your current mortgage with a new one. People do it to lower the rate, change the term, remove PMI, or take cash out of equity. The new loan pays off the old loan, and you start a new amortization schedule.
The monthly payment may go down for three reasons: a lower rate, a longer term, or both. A lower rate is genuine savings. A longer term is partly a payment stretch: you pay less each month because you are spreading the loan over more years. That can be useful for cash flow, but it is not the same as a cheaper loan.
The break-even formula
Break-even months = closing costs ÷ monthly payment savings
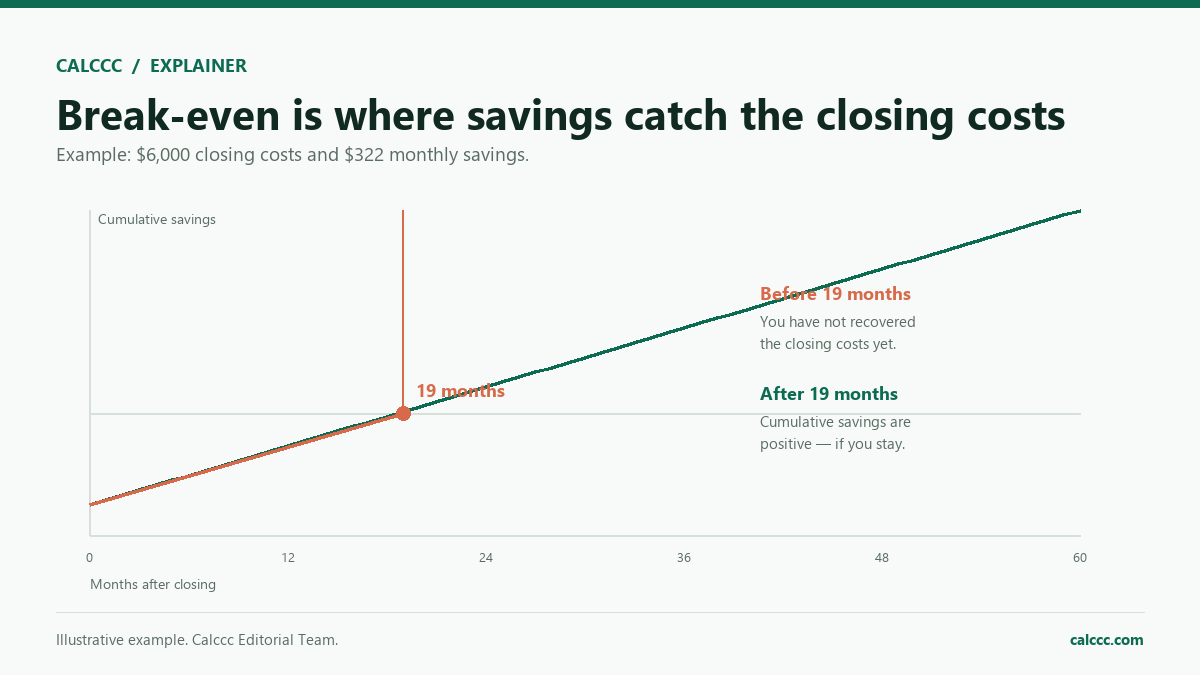
If closing costs are $6,000 and the new payment is $322 lower, break-even is about 19 months. If you stay five years, you have roughly 41 months of savings after recovering the cost. If you move in a year, you may not recover the cost at all.
This is a simple version. It ignores the time value of money, tax deductibility, and changes in taxes and insurance. It is still a useful first screen.
A worked example
Current loan: $300,000 at 7% with 25 years left. New loan: $300,000 at 6% for 30 years. Closing costs: $6,000. The current principal-and-interest payment is about $2,120. The new payment is about $1,799. Monthly savings: $322.
| Item | Current loan | New loan |
|---|---|---|
| Rate | 7.0% | 6.0% |
| Term remaining | 25 years | 30 years |
| Monthly P&I | $2,120 | $1,799 |
| Monthly savings | — | $322 |
| Closing costs | — | $6,000 |
| Break-even | — | 18.7 months |
Here is the catch: the new 30-year loan may have higher lifetime interest than the 25-year loan, even at a lower rate. In our calculator run, lifetime interest savings were negative. The payment is lower, but the loan runs longer. If you want the rate cut without stretching the term, ask for a 25-year or 20-year refinance and compare again.
Cash-out refinance: a different decision
A cash-out refinance replaces the mortgage with a larger loan and gives you the difference in cash. It can be used for home improvements, debt consolidation, or emergencies. It also increases the balance and the interest cost. The break-even calculation should include the higher loan amount, not just the rate change.
Cash-out is not free money. You are borrowing against your home, and you could lose the home if you cannot repay. If the goal is to consolidate high-interest debt, compare the new mortgage rate and term with the debt payoff plan; a longer mortgage can look cheap monthly while costing more overall.
What to compare on the Loan Estimate
| Line item | Why it matters |
|---|---|
| Interest rate | Drives the payment and total interest. |
| APR | Includes some fees; useful for comparing similar loans. |
| Closing costs | Determines break-even and cash needed at closing. |
| Loan term | Changes the payment and lifetime interest. |
| Points | Upfront fee for a lower rate; needs its own break-even. |
| Prepayment penalty | Could cost you if you pay off or refinance again. |
When refinancing is usually not worth it
- You plan to move before the break-even date.
- The rate drop is small and closing costs are high.
- The new term is much longer and you care about total interest.
- You are using cash-out to fund spending without a repayment plan.
- The new payment is only lower because taxes or insurance were left out of the comparison.
2026 calculator update: what changed
The linked calculator has been upgraded. It now includes a professional worksheet with the inputs used, the method and scope, and a one-variable sensitivity check for finance tools. You can save two input sets as Scenarios A/B and compare the results side by side. The Print / PDF action produces a branded worksheet, and table-producing calculators can export a CSV.
The page also explains why a bank, lender, broker, or provider can quote a different number: rate versus APR, fees, credit pricing, taxes, insurance, and timing. Use the written quote or Loan Estimate as the binding document, not the calculator estimate.
2026 professional upgrade: current vs new, side by side
The Calccc mortgage refinance calculator now shows a current-versus-new comparison, a break-even schedule, new loan-to-value, term change, and net benefit over the years you expect to stay. Enter a home value and stay horizon in Advanced options to make the LTV and payback views more useful.
The break-even is still a simple payback: closing costs divided by monthly savings. A longer new term can lower the payment while increasing lifetime interest, so compare the monthly saving with the total interest and the time you expect to stay. A/B scenarios let you compare a rate-and-term refinance with a cash-out version without retyping every field.
Frequently asked questions
How long is a good break-even?
There is no universal number. A shorter break-even is less risky. If you expect to stay in the home well past the break-even, the refinance has more time to pay off. If you may move soon, be conservative.
Should I refinance to remove PMI?
Sometimes. If a simple PMI cancellation request would work, refinancing may be unnecessary. If the loan type or servicer prevents removal, a refinance can solve it, but compare closing costs and the new term.
Is a lower monthly payment always good?
No. A longer term can lower the payment while increasing total interest. Compare the total cost and the payoff date.
Do I need a new appraisal?
Many refinances require an appraisal, but some programs waive it. Ask the lender and include the cost in your break-even.
How we checked this guide
We ran the example through the refinance calculator with the same balance and closing costs, then compared the monthly payment and lifetime interest. The CFPB’s Loan Estimate explainer was used to identify the cost lines to compare. The numbers are illustrative and do not include taxes, insurance, or lender-specific fees.
Further reading
Keep exploring
Decision path