


Key takeaways
- Ask the servicer to apply extra money to principal, not to next month’s payment.
- Even small recurring extras can cut years and interest.
- A one-time payment early can be more powerful than the same amount later.
- Check for prepayment penalties and confirm the new payoff date.
- High-interest debt and emergency savings may deserve the money first.
Why extra principal works
Mortgage interest is charged on the remaining balance. When you send an extra $100 and the servicer applies it to principal, the balance drops by $100. Next month, interest is calculated on a slightly smaller number. That small difference repeats every month, which is why the effect grows over time.
Think of it like walking up a down escalator. The regular payment keeps you in place; extra principal moves you up faster. The earlier you start, the more steps you avoid.
What $100 a month actually does
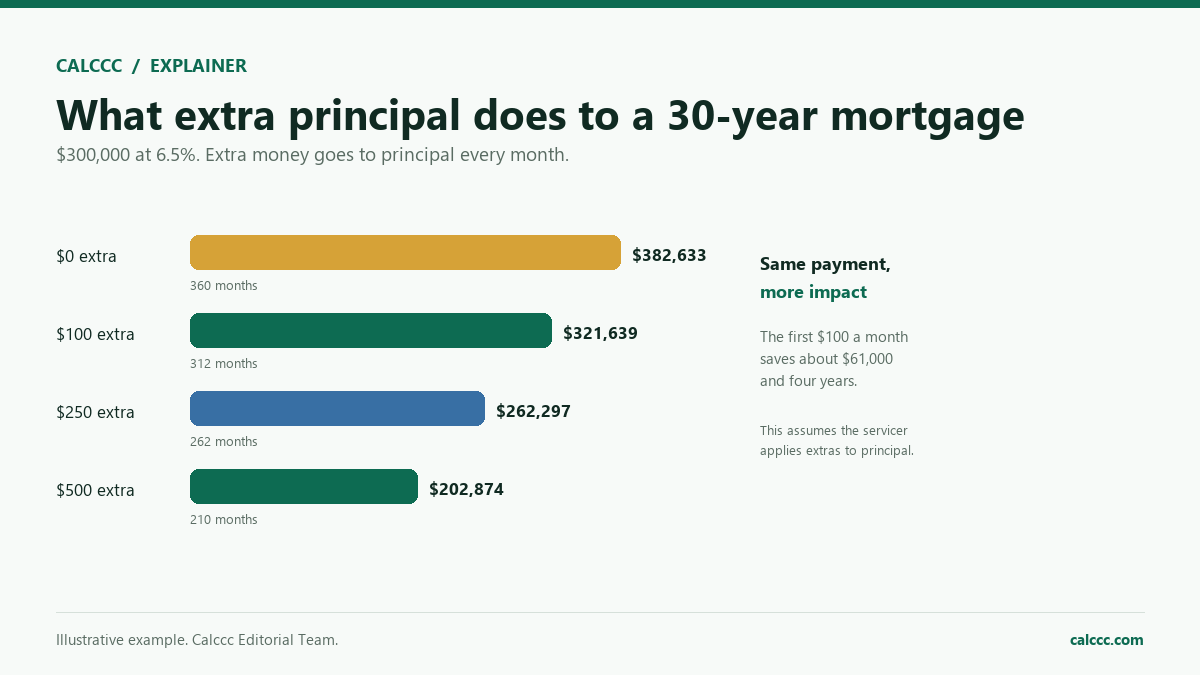
Example: $300,000 at 6.5% for 30 years. The regular principal-and-interest payment is about $1,896. Here is what happens with different extra amounts, assuming the servicer applies them to principal every month:
| Extra per month | Payoff time | Total interest | Interest saved |
|---|---|---|---|
| $0 | 30 years | $382,633 | — |
| $100 | 26 years | $321,639 | $60,995 |
| $250 | 21.8 years | $262,297 | $120,337 |
| $500 | 17.5 years | $202,874 | $179,759 |
The payoff time is rounded. The point is not the exact month; it is the direction and the size of the effect. A $100 extra payment is not trivial over 30 years.
Monthly extra vs. one-time payment
A one-time $10,000 payment in year one has more time to reduce interest than the same $10,000 paid in year 10. But a monthly extra payment is easier to sustain and can be automated. Many people use a combination: a small recurring amount plus a lump sum when a bonus or tax refund arrives.
Before making a lump-sum payment, confirm the servicer’s process. Some require a written instruction or a specific payment type. Keep a confirmation showing the money was applied to principal.
How to set it up correctly
- Call the servicer or use the portal to confirm how extra payments are applied.
- Choose “principal only” if that option exists.
- Set up automatic extra payments if the servicer supports it.
- Check the statement after the first payment to confirm the principal balance dropped.
- Ask for an updated payoff date or amortization schedule.
- Review once a year; adjust if income or goals change.
When extra mortgage payments are not the best move
- High-interest debt: paying off a 24% credit card usually beats prepaying a 6.5% mortgage.
- No emergency fund: cash in the house is hard to access; keep a buffer first.
- Employer retirement match: not capturing a match can be a larger loss than the mortgage interest saved.
- Prepayment penalty: check the loan terms before making a large extra payment.
- Low liquidity: if the extra money leaves you unable to handle a repair or job loss, pause.
Biweekly payments: the same idea in a different wrapper
Biweekly payment plans often collect half the monthly payment every two weeks. Because there are 26 biweekly periods in a year, that is 13 full monthly payments instead of 12 — one extra payment per year. The effect is similar to making one extra monthly payment annually. Some servicers charge a setup fee; a DIY monthly extra payment can achieve the same result without the fee.
2026 calculator update: what changed
The linked calculator has been upgraded. It now includes a professional worksheet with the inputs used, the method and scope, and a one-variable sensitivity check for finance tools. You can save two input sets as Scenarios A/B and compare the results side by side. The Print / PDF action produces a branded worksheet, and table-producing calculators can export a CSV.
The page also explains why a bank, lender, broker, or provider can quote a different number: rate versus APR, fees, credit pricing, taxes, insurance, and timing. Use the written quote or Loan Estimate as the binding document, not the calculator estimate.
Frequently asked questions
Does extra money always go to principal?
Not automatically. It depends on the servicer and how you instruct the payment. Confirm in writing or in the portal that it is applied to principal.
Is it better to pay extra monthly or in a lump sum?
Earlier money saves more interest, so a lump sum early is powerful. A monthly plan is easier to sustain. Choose based on cash flow and discipline, not just the theoretical optimum.
Can I pay off my mortgage early?
Often yes, but check for prepayment penalties and make sure the servicer applies the final payment correctly. You may need to request a payoff statement.
Should I invest instead?
That depends on the mortgage rate, expected after-tax return, risk tolerance, and liquidity. A guaranteed interest saving is not directly comparable to a risky investment return.
How we checked this guide
We used the same amortization engine as the mortgage calculator, with no fees or rate changes, and compared total interest and payoff month for each extra amount. The servicer application process is described generally; individual servicers may differ.
Further reading
Keep exploring
Decision path