


What this calculator does
This mortgage refinance calculator compares your current loan with a proposed new loan. It uses standard amortization to estimate each principal-and-interest payment and the total interest over each term. It also shows how long monthly savings take to cover closing costs and whether the new loan saves money overall. Use it to compare a lower rate, a shorter term, or a longer term.
Is this the right calculator?
Use it when
- You are comparing a new mortgage rate with your current loan.
- You want to estimate the monthly saving and the break-even month.
Use something else when
- You need a cash-out refinance with a changing loan balance.
- You need lender-specific closing costs, points, or escrow adjustments.
What changes the result most
| Rate change | The bigger the drop from your current rate, the larger the monthly saving. |
|---|---|
| Closing costs | Higher costs push the break-even month further out. |
| Remaining term | A shorter new term raises the payment even when the rate falls. |
How to use it
- Enter the current balance, current rate, and remaining term.
- Enter the new rate, new term, and closing costs.
- Open Advanced options to add cash-out, finance closing costs, a home value for LTV, or a different stay horizon.
- Compare the current and new monthly payments, then check the break-even and lifetime interest.
- Review the net benefit over the years you expect to stay; a longer term can lower the payment while raising total interest.
How it works
Example calculations
Example 1: $300,000 balance
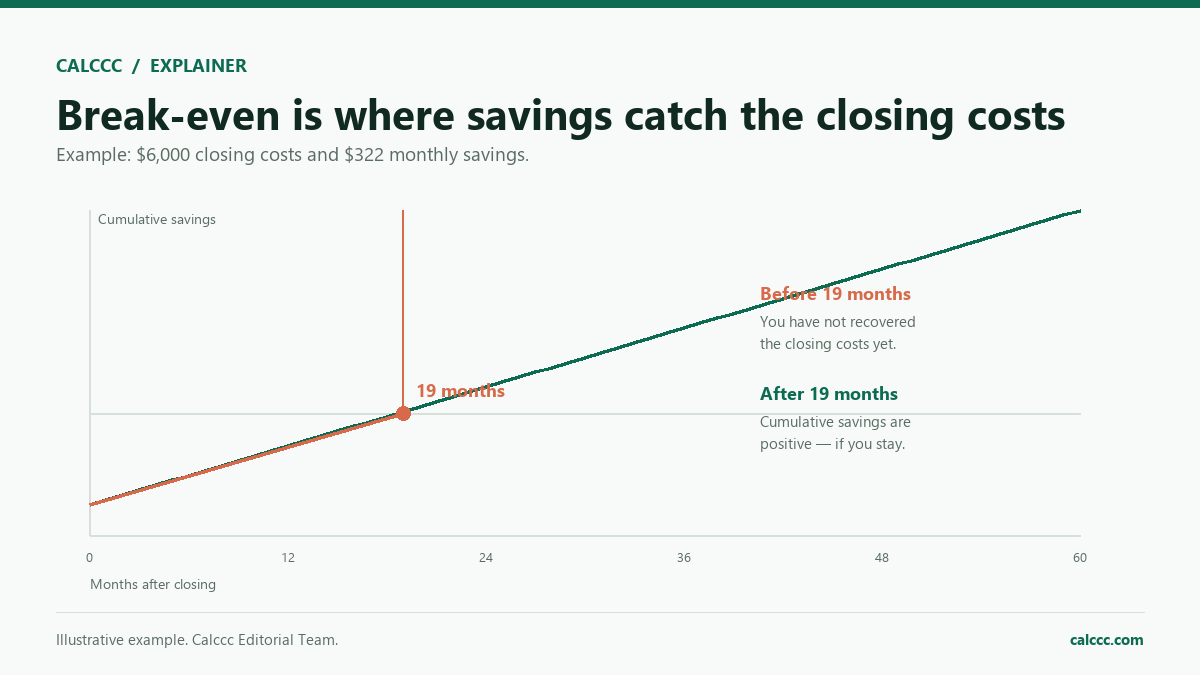
$300,000 at 7% with 25 years left: payment about $2,120 and interest about $336,101. At 6% for 30 years: payment about $1,799, interest about $347,515, and monthly savings about $322. Closing costs of $6,000 break even in about 19 months, but the extra interest and closing costs leave net savings at -$17,413.
Example 2: $250,000 balance
$250,000 at 6.5% with 20 years left: payment about $1,864 and interest about $197,344. At 5.75% for 20 years: payment about $1,755, interest about $171,250, and monthly savings about $109. With $4,000 closing costs, break-even is about 37 months and net savings about $22,094.
Example 3: $400,000 balance
$400,000 at 7.5% with 30 years left: payment about $2,797 and interest about $606,869. At 6.75% for 30 years: payment about $2,594, interest about $533,981, and monthly savings about $202. Closing costs of $8,000 break even in about 40 months, with net savings about $64,888.
What the result means
Break-even is the point when the monthly payment savings equal the closing costs you paid. It does not by itself show whether the refinance is worthwhile. A lower rate usually saves interest, but a longer term can lower the payment while raising total interest, as the first example shows. A shorter term can raise the payment and cut total interest. Closing costs vary by lender and location, and some costs may be rolled into the loan instead of paid upfront. Compare the new loan's total cost over the time you plan to stay in the home, not only the monthly payment.
Common mistakes
- Comparing only monthly payments and ignoring total interest.
- Choosing a new term longer than the time you plan to stay.
- Leaving out closing costs or financing them without adjusting the balance.
- Using the wrong remaining balance or term.
- Assuming the advertised rate is guaranteed.
Assumptions and limits
- Both loans have fixed rates and equal monthly payments.
- Closing costs are paid upfront unless you choose to finance them.
- The new loan replaces the current balance, plus any cash-out and financed closing costs.
- The current loan has no prepayment penalty.
- The stay horizon is a planning input, not a prediction.
- Taxes, insurance, HOA, and tax deductibility are excluded.
Frequently asked questions
How is break-even calculated?
Closing costs divided by the monthly payment savings. If the new payment is higher, break-even is not defined.
Does cash-out refinancing increase the loan?
Yes. The cash-out amount is added to the new loan, so the payment and interest increase.
Should I finance closing costs?
It preserves cash but increases the loan balance and interest. Compare both options.
Why is lifetime interest savings negative?
A longer new term or higher new loan can increase total interest even when the monthly payment falls.
Does this include taxes and insurance?
No. It compares principal and interest. Taxes, insurance, and HOA are separate and may change after closing.
Can I use this for a rate-and-term refinance?
Yes. Set cash-out to zero and enter the new rate, term, and closing costs.
What is the net benefit over my stay?
It is the monthly payment savings multiplied by the number of months you expect to stay, minus closing costs. It is a simpler payback view than lifetime interest.
Why does a longer new term sometimes look cheaper monthly?
A longer term spreads the balance over more payments, lowering the monthly payment but often increasing total interest. Compare both the payment and the lifetime cost.
Sources
2026 update
How to use the professional output
This page is not just a formula box. The result is designed to be checked, compared, and taken away.
- Professional worksheet. The result includes the inputs used, the method and scope, and a one-variable sensitivity check for finance calculators.
- A/B scenarios. Save two input sets in the browser and compare the primary, secondary, and breakdown figures side by side.
- Print / PDF and CSV. Print a branded worksheet, or export the year-by-year table when the calculator produces one.
- Quote differences. The section below explains why a bank, lender, broker, or provider can quote a different number.
The formulas and assumptions above still govern the number. The worksheet makes the estimate auditable; it does not make it a lender quote, tax return, or personalized advice.
Before you use a quote
Why your bank, lender, or provider’s number may differ
A mortgage quote can differ from this estimate even when the loan amount and rate look the same. The lender’s Loan Estimate is the document that controls the actual offer.
What changes the quote
- Rate versus APR. Points, lender credits, and closing costs can make the APR different from the note rate.
- Escrow and insurance. Property tax, homeowners insurance, PMI, and HOA are local and lender-specific.
- Loan-level pricing. Credit score, down payment, occupancy, property type, and loan size can change the rate.
- Timing. Rates can change daily; a quote is not a lock until it is locked in writing.
How to compare offers
- Compare the APR and total cost, not only the monthly payment.
- Ask for a written quote or Loan Estimate with all fees itemized.
- Use the same loan amount, term, date, and assumptions for every offer.
- Check what is excluded: taxes, insurance, closing costs, maintenance, or provider fees.
- Keep an emergency reserve; the lowest payment is not always the safest choice.
Reference: CFPB Loan Estimate explainer.
Part of a decision center
Mortgage & Home Buying Center
See the companion tools, decision guides, and patterns that go with this calculator.
Go deeper
Guides that explain the math

The Refinance Reset: Why a Lower Payment Can Cost More
A refinance restarts the clock. Compare the break-even month, remaining term, closing costs, and cash-out risk before choosing a lower payment.
Refinance Break-Even: When Closing Costs Are Worth It
A lower rate is not enough. We explain break-even in plain English, compare a 30-year reset with a shorter term, and show the cash-out trap.