What this calculator does
Rental yield compares the income a property produces with the price paid for it. Gross yield uses rent before expenses; net yield subtracts vacancy loss and operating costs. Neither number includes the mortgage payment, income tax, or closing costs, so treat them as screening tools rather than a full cash-flow projection.
How to use it
- Enter the purchase price you would pay, not the list price plus repairs you have not budgeted.
- Enter the monthly rent you expect after the property is stabilized.
- Add annual operating expenses: property tax, insurance, maintenance, management, HOA, and utilities paid by the owner.
- Set a realistic vacancy rate rather than assuming 100% occupancy.
- Compare gross yield, net yield, and monthly net operating income.
How it works
Example calculations
Example: $350,000 property at $2,200 rent
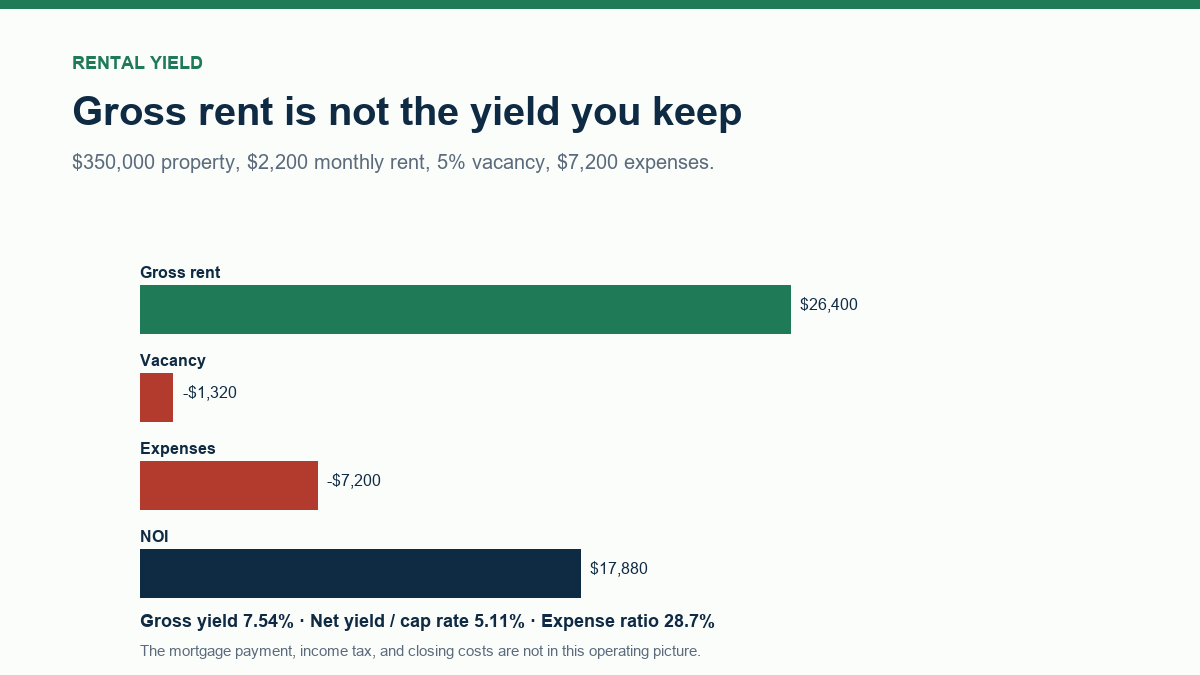
Gross rent is $26,400. At 5% vacancy, the loss is $1,320, leaving $25,080 of effective income. With $7,200 of operating expenses, NOI is $17,880. Gross yield is 7.54%; net yield is 5.11%; the expense ratio is 28.7%.
Why the mortgage is excluded
NOI is a property-level measure. Two buyers can pay different prices and use different loans, but the property's operating income is the same. Including one buyer's mortgage would make the yield impossible to compare.
What the result means
A higher net yield means more income per dollar of price, but it can also signal higher risk, older construction, or a market with weak appreciation. Compare properties in the same market and use the same expense assumptions. A low yield can still make sense if the property is expected to appreciate, but that is a separate bet.
Common mistakes
- Using gross rent and ignoring vacancy and operating expenses.
- Including the mortgage payment in operating expenses instead of treating it as financing.
- Understating maintenance, management, or future capital repairs.
- Comparing yields across markets without adjusting for taxes, insurance, and risk.
Assumptions and limits
- Rent is stabilized and collected monthly.
- Operating expenses are annual and exclude debt service and income tax.
- No closing costs, renovation costs, or capital expenditure reserve are included.
- The property is purchased for cash in the yield calculation.
Frequently asked questions
What is the difference between gross yield and net yield?
Gross yield uses annual rent before expenses. Net yield subtracts vacancy loss and operating expenses, so it is closer to the property's actual operating return.
Is net rental yield the same as cap rate?
In this calculator, yes. Both use net operating income divided by purchase price. Some markets use different definitions, so compare the same formula.
Should the mortgage payment be included?
No. Net operating income is a property-level measure before financing. Mortgage payments depend on the buyer's loan and down payment.
What vacancy rate should I use?
Use a local, property-specific estimate. A common starting point is one month of vacancy per year, but the right number depends on the market and unit type.
Sources
2026 update
How to use the professional output
This page is not just a formula box. The result is designed to be checked, compared, and taken away.
- Professional worksheet. The result includes the inputs used, the method and scope, and a one-variable sensitivity check for finance calculators.
- A/B scenarios. Save two input sets in the browser and compare the primary, secondary, and breakdown figures side by side.
- Print / PDF and CSV. Print a branded worksheet, or export the year-by-year table when the calculator produces one.
- Quote differences. The section below explains why a bank, lender, broker, or provider can quote a different number.
The formulas and assumptions above still govern the number. The worksheet makes the estimate auditable; it does not make it a lender quote, tax return, or personalized advice.
Before you use a quote
Why your bank, lender, or provider’s number may differ
A mortgage quote can differ from this estimate even when the loan amount and rate look the same. The lender’s Loan Estimate is the document that controls the actual offer.
What changes the quote
- Rate versus APR. Points, lender credits, and closing costs can make the APR different from the note rate.
- Escrow and insurance. Property tax, homeowners insurance, PMI, and HOA are local and lender-specific.
- Loan-level pricing. Credit score, down payment, occupancy, property type, and loan size can change the rate.
- Timing. Rates can change daily; a quote is not a lock until it is locked in writing.
How to compare offers
- Compare the APR and total cost, not only the monthly payment.
- Ask for a written quote or Loan Estimate with all fees itemized.
- Use the same loan amount, term, date, and assumptions for every offer.
- Check what is excluded: taxes, insurance, closing costs, maintenance, or provider fees.
- Keep an emergency reserve; the lowest payment is not always the safest choice.
Reference: CFPB Loan Estimate explainer.
Go deeper