


What this calculator does
This credit card payoff calculator shows what a fixed monthly payment does to a balance and how much goes to interest along the way. Cards compound daily in practice, but a monthly model gets close enough for planning. Use it to compare $200 a month with $300, to test a lower APR, or to see how long a minimum payment would take.
Is this the right calculator?
Use it when
- You have a balance, APR, and fixed monthly payment and want a payoff date.
- You want to see how much interest a payment plan costs.
- You want to test a higher monthly payment and see the yearly interest schedule.
Use something else when
- You are comparing multiple cards and want a debt-snowball or avalanche order.
- You need an issuer-specific minimum-payment formula or promotional APR schedule.
What changes the result most
| APR | A higher interest rate makes each payment cover less principal. |
|---|---|
| Monthly payment | Paying more shortens the payoff time and reduces interest. |
| Balance | A larger starting balance takes longer to clear at the same payment. |
| Extra payment | Extra principal shortens payoff and reduces total interest. |
How to use it
- Enter the current balance, APR, and the monthly payment you can make.
- Open Advanced options to add an extra monthly payment or a payoff start date.
- Review months to payoff, total interest, total paid, and payoff date.
- Open Advanced options to set a minimum-payment percentage and dollar floor.
- Compare your payment with the minimum-payment scenario and review the year-by-year table.
How it works
Example calculations
Example 1: ,000 at 22%
A monthly payment takes about 34 months and costs about ,750 in interest.
Example 2: extra
Adding /month shortens payoff and reduces interest; the table shows the new yearly interest total.
Example 3: payment too low
If the payment is less than the monthly interest, the calculator warns that the balance never falls and asks for a larger payment.
What the result means
The result assumes no new charges, a fixed APR, and a fixed payment. Minimum payments often fall as the balance drops, which stretches payoff; this calculator holds the payment constant unless you add an extra amount. Balance transfers, fees, and promotional rates are not modeled.
Common mistakes
- Paying only the minimum and assuming the payoff date stays fixed.
- Missing a payment, which can trigger a penalty APR.
- Adding new charges while trying to pay off the balance.
- Ignoring balance-transfer fees and promotional-rate expiry.
- Comparing monthly payments without comparing total interest.
Assumptions and limits
- No new charges are added.
- The APR is fixed for the full payoff period.
- The payment stays constant.
- Extra payments are applied every month.
- The payoff date assumes the first payment is one month after the start date.
Frequently asked questions
Why does my card payoff take longer?
Minimum payments often drop as the balance falls, so more of each payment goes to interest. This calculator holds the payment constant; actual issuers may reduce it.
How is a minimum payment set?
Issuers usually use a percentage of the balance plus interest, with a floor. Check your statement; this calculator uses the payment you enter.
Does a 0% balance transfer help?
It can, but transfer fees and the rate after the promotional period matter. This calculator assumes a fixed APR and does not model promotions.
Can I pay the card off faster?
Yes. Add an extra monthly payment or increase the base payment; the calculator shows interest saved and months saved.
What if I can only cover the interest?
The balance never falls. The calculator warns you and shows no payoff date.
Does paying off a card hurt my credit?
Paying down revolving debt can help utilization, but closing the account may affect credit history. This is not credit advice.
Are new charges included?
No. New charges change the payoff math; add them to the balance or recalculate after they post.
Why is my actual payoff different?
Variable APRs, fees, minimum-payment rules, and new charges change the result. Use this as a planning estimate.
Sources
2026 update
How to use the professional output
This page is not just a formula box. The result is designed to be checked, compared, and taken away.
- Professional worksheet. The result includes the inputs used, the method and scope, and a one-variable sensitivity check for finance calculators.
- A/B scenarios. Save two input sets in the browser and compare the primary, secondary, and breakdown figures side by side.
- Print / PDF and CSV. Print a branded worksheet, or export the year-by-year table when the calculator produces one.
- Quote differences. The section below explains why a bank, lender, broker, or provider can quote a different number.
The formulas and assumptions above still govern the number. The worksheet makes the estimate auditable; it does not make it a lender quote, tax return, or personalized advice.
Before you use a quote
Why your bank, lender, or provider’s number may differ
A lender’s quote can differ from this estimate because the advertised rate is not always the APR, and fees and credit pricing are lender-specific.
What changes the quote
- APR versus interest rate. Origination, documentation, and registration fees are part of the APR but not the note rate.
- Credit and term. A longer term lowers the payment but usually raises total interest.
- Taxes and insurance. Sales tax, registration, and required coverage vary by state and lender.
- Promotional pricing. Dealer or issuer incentives may be conditional and can change the effective cost.
How to compare offers
- Compare the APR and total cost, not only the monthly payment.
- Ask for a written quote or Loan Estimate with all fees itemized.
- Use the same loan amount, term, date, and assumptions for every offer.
- Check what is excluded: taxes, insurance, closing costs, maintenance, or provider fees.
- Keep an emergency reserve; the lowest payment is not always the safest choice.
Reference: CFPB Loan Estimate explainer.
Part of a decision center
Debt & Credit Center
See the companion tools, decision guides, and patterns that go with this calculator.
Go deeper
Guides that explain the math

Debt Payoff Patterns: Minimums, Utilization Timing, and Payoff Order
The repeatable debt patterns that change the answer: minimum-payment traps, statement-date utilization, snowball vs avalanche, and consolidation trade-offs.
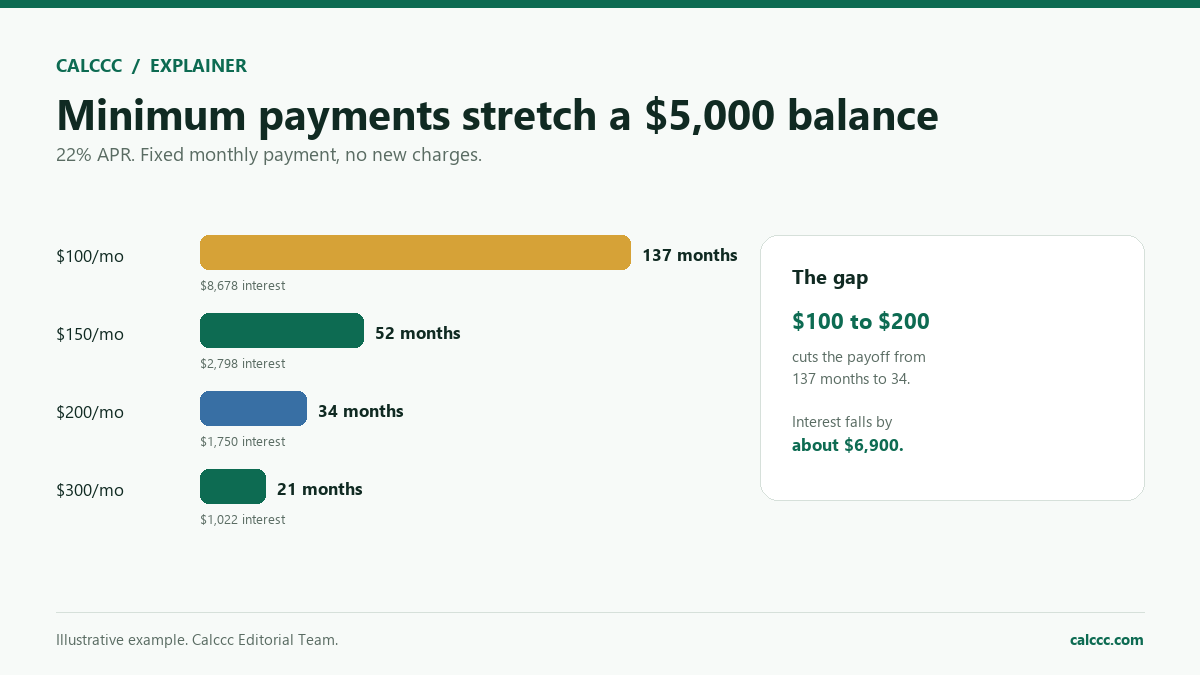
Why Minimum Credit Card Payments Keep You in Debt
Minimum payments are designed to keep the account current, not to pay it off quickly. See the real math on a $5,000 balance and the practical ways out.
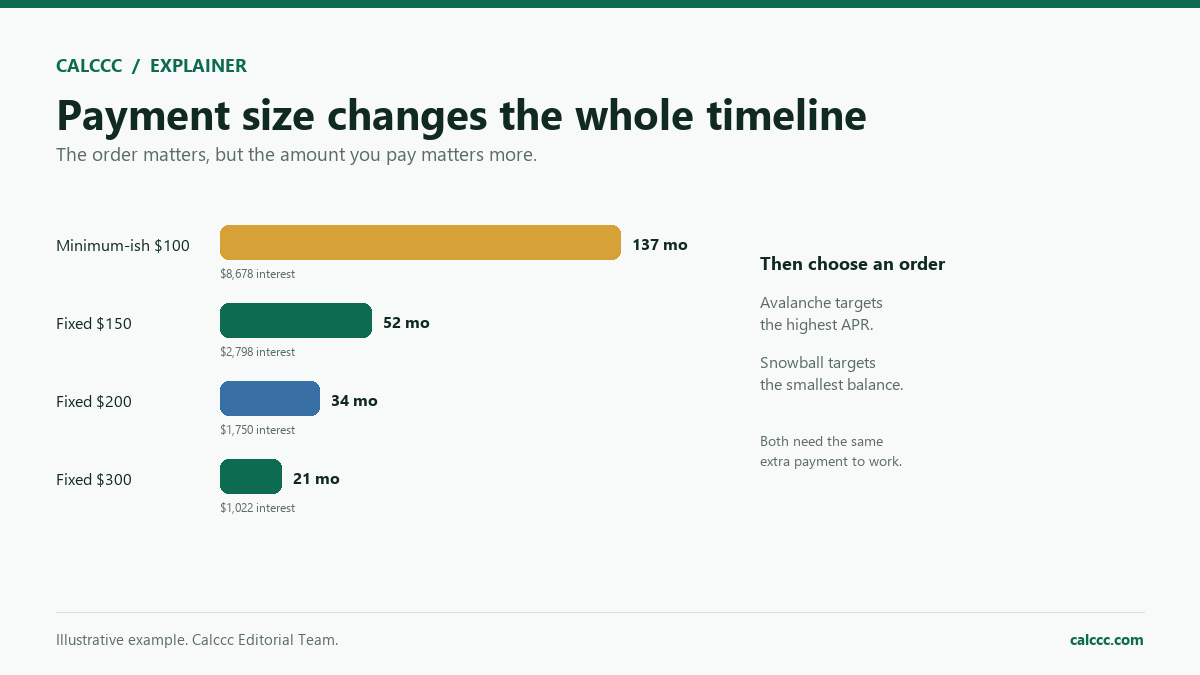
Credit Card Payoff Methods Compared: Which Fits You?
Minimums, snowball, avalanche, balance transfers, and consolidation each solve a different problem. Compare the trade-offs before you pick a plan.