What this calculator does
The debt snowball pays debts from smallest balance to largest, regardless of interest rate. Small wins can build momentum, and each paid-off debt frees its minimum payment for the next one. This calculator runs a month-by-month simulation with interest, minimums, and rolled-over payments so you can see how a plan plays out. It is an estimate for planning, not a payoff guarantee; late fees, new charges, and variable rates can change the path.
How to use it
- Enter each debt balance, APR, and minimum payment.
- Enter an extra monthly amount to put toward debt.
- Review the selected strategy’s payoff order, interest, and months.
- Compare the Snowball and Avalanche results in the secondary panel.
- Review the method comparison table and the annual balance schedule.
- Use A/B scenarios to compare different extra-payment amounts.
How it works
Example calculations
Example 1: $1,000 card, $3,000 loan, $8,000 car, $200 extra
With payments of $50, $100, and $150 plus $200 extra, the snowball clears the card, then the loan, then the car. The plan reaches debt-free in about 33 months, with about $1,125 in interest and $13,125 total paid.
Example 2: $500 card, $2,000 loan, $5,000 car, $100 extra
With payments of $25, $75, and $100 plus $100 extra, the card is paid first, followed by the loan and the car. The plan reaches debt-free in about 38 months, with about $1,342 in interest and $8,842 total paid.
Example 3: one $2,500 balance at 0%, no extra
A single $2,500 balance at 0% with a $100 minimum takes 25 months and costs $2,500, with no interest. The payoff order has one debt; zero-balance entries are ignored.
What the result means
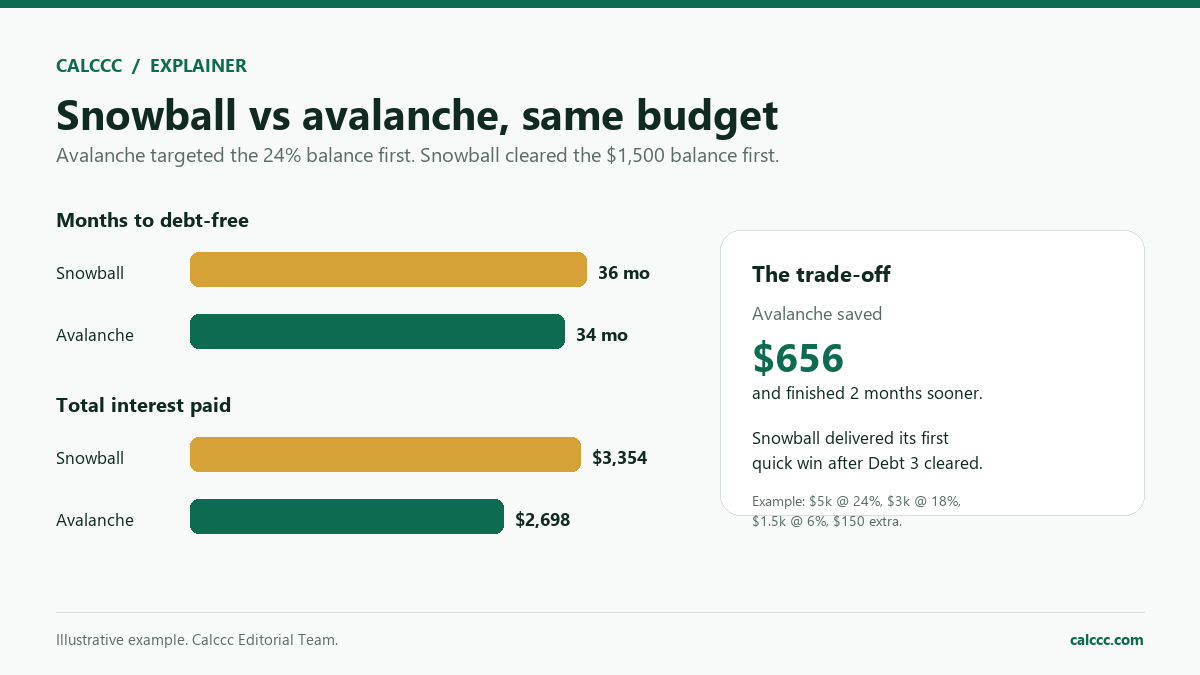
Snowball and avalanche are two ways to order the same payments. Snowball targets the smallest balance first, so you see debts disappear sooner; avalanche targets the highest APR first, which usually minimizes total interest. The best method is the one you can stick with, because missed payments and new borrowing can outweigh a mathematically cheaper order. This simulation assumes you stop adding new charges and that rates and minimums stay fixed. In reality, a variable rate can rise, a minimum can change, and a late fee can undo a month's progress. Compare the debt-free date and total interest, then check the plan against your budget.
Common mistakes
- Continuing to use credit cards while paying them down.
- Forgetting that a minimum payment may not cover monthly interest.
- Using the extra payment on several debts instead of one target.
Assumptions and limits
- Only the three entered debts exist and no new charges are added.
- APRs and minimum payments stay constant for the entire payoff.
- Interest is calculated monthly at APR divided by 12.
- Payments are made on time and the extra amount is available every month.
Frequently asked questions
Which strategy pays less interest?
Avalanche usually pays less interest because extra money targets the highest rate. Snowball may feel easier to follow because it clears small balances first.
Why compare both?
The best strategy is the one you will stick with. The calculator shows the trade-off in months and interest.
Does this include new charges?
No. It assumes no new borrowing and fixed APRs.
Can I add more than three debts?
The current form supports three debts. Combine smaller debts or use the largest three for an estimate.
Why is my payoff different?
Minimum payments, rates, fees, and new charges change the result.
What if my budget does not cover interest?
The payoff may never finish; increase the extra amount or reduce the balances.
Sources
2026 update
How to use the professional output
This page is not just a formula box. The result is designed to be checked, compared, and taken away.
- Professional worksheet. The result includes the inputs used, the method and scope, and a one-variable sensitivity check for finance calculators.
- A/B scenarios. Save two input sets in the browser and compare the primary, secondary, and breakdown figures side by side.
- Print / PDF and CSV. Print a branded worksheet, or export the year-by-year table when the calculator produces one.
- Quote differences. The section below explains why a bank, lender, broker, or provider can quote a different number.
The formulas and assumptions above still govern the number. The worksheet makes the estimate auditable; it does not make it a lender quote, tax return, or personalized advice.
Before you use a quote
Why your bank, lender, or provider’s number may differ
A lender’s quote can differ from this estimate because the advertised rate is not always the APR, and fees and credit pricing are lender-specific.
What changes the quote
- APR versus interest rate. Origination, documentation, and registration fees are part of the APR but not the note rate.
- Credit and term. A longer term lowers the payment but usually raises total interest.
- Taxes and insurance. Sales tax, registration, and required coverage vary by state and lender.
- Promotional pricing. Dealer or issuer incentives may be conditional and can change the effective cost.
How to compare offers
- Compare the APR and total cost, not only the monthly payment.
- Ask for a written quote or Loan Estimate with all fees itemized.
- Use the same loan amount, term, date, and assumptions for every offer.
- Check what is excluded: taxes, insurance, closing costs, maintenance, or provider fees.
- Keep an emergency reserve; the lowest payment is not always the safest choice.
Reference: CFPB Loan Estimate explainer.
Part of a decision center
Debt & Credit Center
See the companion tools, decision guides, and patterns that go with this calculator.
Go deeper