What this calculator does
This loan calculator goes beyond the payment: it shows how much of each year goes to principal and interest, what fees add to the total, and how extra payments change the payoff date. Use it for personal loans, auto loans, student loans, or any fixed-rate installment loan. It does not model variable rates, income-driven repayment, deferment, or lender-specific fee rules.
Is this the right calculator?
Use it when
- You are comparing fixed-rate installment loans with the same repayment period.
- You want to see how much of the total cost is interest rather than principal.
- You want to test extra monthly or one-time payments, origination fees, or a yearly amortization schedule.
Use something else when
- You need a revolving credit or credit-card payoff plan rather than a fixed installment loan.
- You need a month-by-month amortization statement for a lender or tax filing.
What changes the result most
| Interest rate | A higher rate increases both the monthly payment and total interest. |
|---|---|
| Term length | Stretching the term lowers the payment but raises lifetime interest. |
| Amount borrowed | The payment scales with the principal, so a smaller loan costs less each month. |
| Extra payments | Extra principal reduces future interest and can shorten the payoff period. |
| Fees | Origination fees raise total cost but do not change the monthly payment in this estimate. |
How to use it
- Enter the loan amount, annual interest rate, and term.
- Open Advanced options to add origination fees, extra monthly payments, a one-time extra payment, or a start date.
- Review the monthly payment, total interest, total paid, and payoff date.
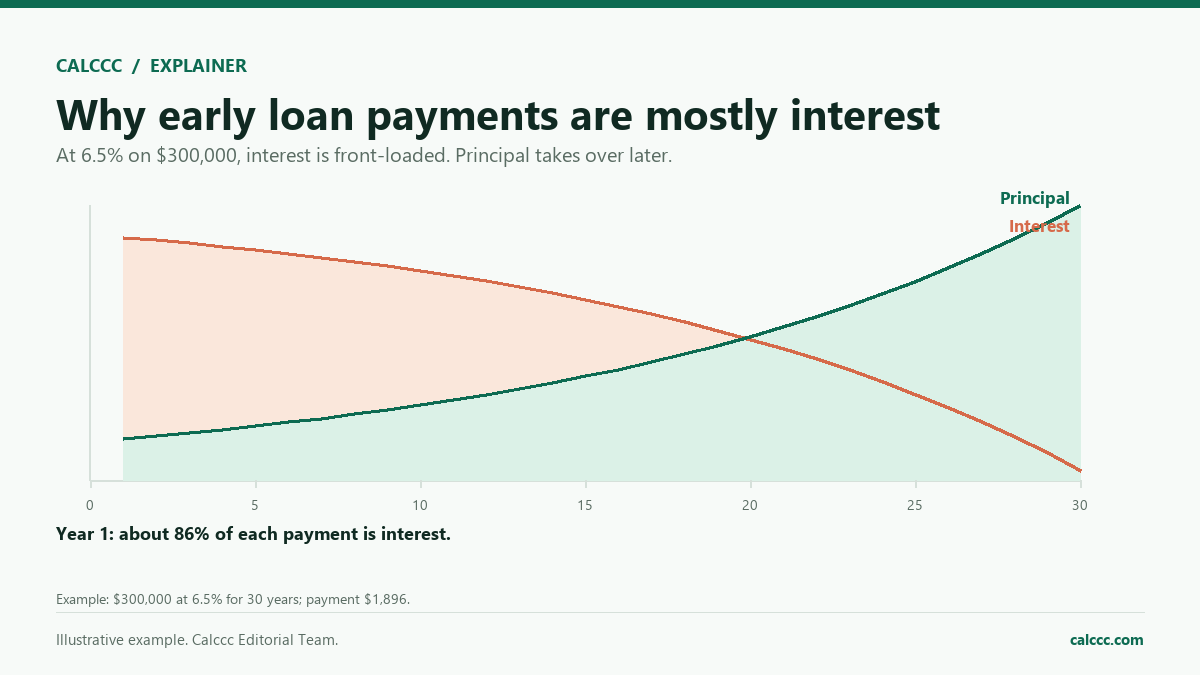
- Check the yearly amortization schedule to see the principal and interest split.
- Change one input at a time to compare a shorter term or a larger extra payment.
How it works
Example calculations
Example 1: 5-year personal loan
A $25,000 loan at 7.5% over 5 years has a monthly payment of about $501. Total interest is about $5,057 and total paid is about $30,057 before fees.
Example 2: extra monthly payment
Adding $100/month to the same loan reduces the balance faster and can cut both total interest and the number of payments. The exact savings depend on when the extra payments start.
Example 3: origination fee
A $500 origination fee does not change the monthly payment in this estimate, but it raises total cost. Confirm whether your lender deducts the fee from the proceeds or adds it to the balance.
What the result means
The monthly payment is the fixed principal-and-interest amount. Fees, late charges, insurance, and other add-ons are separate. A shorter term usually raises the monthly payment but lowers total interest. Extra payments save the most when made early. The table is a yearly summary, not a lender statement, and it assumes the rate and payment stay constant.
Common mistakes
- Using the monthly payment as the total cost.
- Forgetting origination fees or add-on products.
- Assuming extra payments automatically shorten the term; confirm the lender applies them to principal.
- Comparing loans with different terms without comparing total interest.
- Using a variable-rate loan as if the rate were fixed.
- Ignoring taxes, insurance, or other costs that are not part of the loan.
Assumptions and limits
- The loan has a fixed interest rate.
- Payments are monthly and on time.
- Origination fees are paid upfront and added to total cost, not financed.
- Extra payments are applied to principal with the first payment and stay constant.
- The payoff date assumes the first payment is one month after the start date.
- Taxes, insurance, and other add-ons are not included.
Frequently asked questions
Does this include fees?
You can add an origination fee. It increases total cost but is not financed in this estimate. Confirm how your lender treats fees.
How do extra payments reduce interest?
Extra money goes to principal, so future interest is charged on a smaller balance. The calculator shows interest saved and months saved.
What is the difference between total interest and total paid?
Total interest is only the cost of borrowing. Total paid includes the loan amount, interest, and origination fees.
Can I use this for a mortgage?
For a mortgage with taxes, insurance, HOA, and PMI, use the dedicated Mortgage Calculator.
Why does a shorter term cost less in total?
You pay interest for fewer months, but the monthly payment is higher because the principal is repaid faster.
Does this work for variable-rate loans?
No. It assumes a fixed rate for the full term.
Can I see a monthly amortization schedule?
The page shows a yearly summary. A monthly schedule can be generated from the same formula if needed.
Why is my actual payment different?
Lender fees, insurance, taxes, rounding, and add-ons can change the amount. Use this as a planning estimate.
Sources
2026 update
How to use the professional output
This page is not just a formula box. The result is designed to be checked, compared, and taken away.
- Professional worksheet. The result includes the inputs used, the method and scope, and a one-variable sensitivity check for finance calculators.
- A/B scenarios. Save two input sets in the browser and compare the primary, secondary, and breakdown figures side by side.
- Print / PDF and CSV. Print a branded worksheet, or export the year-by-year table when the calculator produces one.
- Quote differences. The section below explains why a bank, lender, broker, or provider can quote a different number.
The formulas and assumptions above still govern the number. The worksheet makes the estimate auditable; it does not make it a lender quote, tax return, or personalized advice.
Before you use a quote
Why your bank, lender, or provider’s number may differ
A lender’s quote can differ from this estimate because the advertised rate is not always the APR, and fees and credit pricing are lender-specific.
What changes the quote
- APR versus interest rate. Origination, documentation, and registration fees are part of the APR but not the note rate.
- Credit and term. A longer term lowers the payment but usually raises total interest.
- Taxes and insurance. Sales tax, registration, and required coverage vary by state and lender.
- Promotional pricing. Dealer or issuer incentives may be conditional and can change the effective cost.
How to compare offers
- Compare the APR and total cost, not only the monthly payment.
- Ask for a written quote or Loan Estimate with all fees itemized.
- Use the same loan amount, term, date, and assumptions for every offer.
- Check what is excluded: taxes, insurance, closing costs, maintenance, or provider fees.
- Keep an emergency reserve; the lowest payment is not always the safest choice.
Reference: CFPB Loan Estimate explainer.
Part of a decision center
Loan Center
See the companion tools, decision guides, and patterns that go with this calculator.
Go deeper