What this calculator does
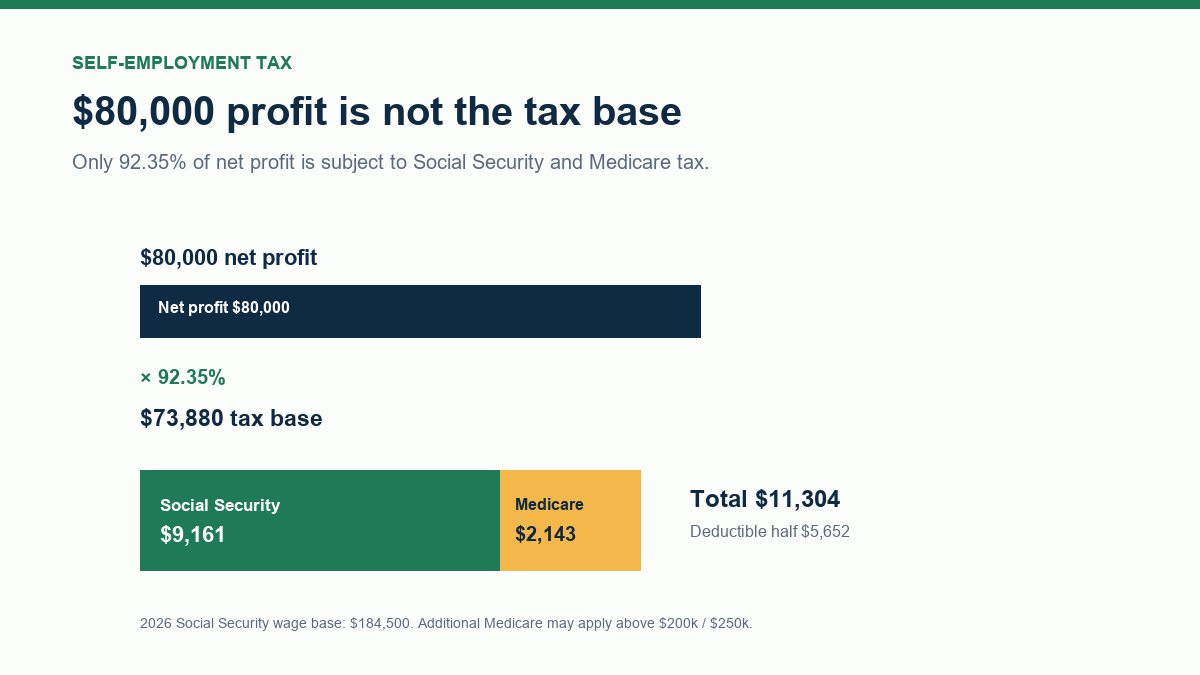
Self-employed workers generally pay both the employee and employer portions of Social Security and Medicare tax. The tax is calculated on net earnings, not gross revenue, and only 92.35% of net profit is subject to the tax. Half of the self-employment tax is deductible for income tax purposes, but it does not reduce the self-employment tax itself.
How to use it
- Enter net self-employment profit after business expenses.
- Add any W-2 wages that were already subject to Social Security tax.
- Choose single or married filing jointly for the Additional Medicare threshold.
- Review the Social Security, Medicare, and Additional Medicare components.
- Review the quarterly table and keep the set-aside separate from operating cash.
- Remember that this is self-employment tax only, not federal income tax.
How it works
Example calculations
Example: $80,000 net profit, no W-2 wages
Net earnings are $73,880. Social Security is $9,161 and Medicare is $2,143, for $11,304 before Additional Medicare. The deductible half is about $5,652, and a flat quarterly set-aside is about $2,826.
Example with W-2 wages
If you already earned $150,000 in W-2 wages, only $34,500 of the 2026 wage base remains. The Social Security portion is calculated on that remaining room, while Medicare still applies to the self-employment earnings.
What the result means
The result is the self-employment tax only. It does not include federal income tax, state income tax, local tax, or credits. The deductible half lowers taxable income but not the self-employment tax. Use the estimate with a full tax projection or a tax professional, especially if you have multiple income sources or owe Additional Medicare tax.
Common mistakes
- Applying the tax to gross revenue instead of net profit.
- Forgetting the 92.35% adjustment.
- Ignoring W-2 wages when applying the Social Security wage base.
- Treating the deductible half as a payment or credit.
- Assuming the quarterly set-aside covers income tax too.
Assumptions and limits
- Net profit is subject to self-employment tax.
- The 2026 Social Security wage base is $184,500.
- Additional Medicare thresholds are $200,000 single and $250,000 married filing jointly.
- Only self-employment tax is estimated; income tax and state tax are excluded.
Frequently asked questions
What income is subject to self-employment tax?
Generally, net earnings from self-employment. The calculator applies the 92.35% adjustment to net profit before calculating Social Security and Medicare.
Why is only 92.35% of profit taxed?
The adjustment approximates the employer portion of the tax that would be paid on wages. It is part of the Schedule SE calculation.
Does the deductible half reduce self-employment tax?
No. It is an income tax deduction. It reduces taxable income, not the self-employment tax itself.
Does this include federal income tax?
No. It estimates self-employment tax only. Use a full tax projection for income tax, credits, and state tax.
Sources
2026 update
How to use the professional output
This page is not just a formula box. The result is designed to be checked, compared, and taken away.
- Professional worksheet. The result includes the inputs used, the method and scope, and a one-variable sensitivity check for finance calculators.
- A/B scenarios. Save two input sets in the browser and compare the primary, secondary, and breakdown figures side by side.
- Print / PDF and CSV. Print a branded worksheet, or export the year-by-year table when the calculator produces one.
- Quote differences. The section below explains why a bank, lender, broker, or provider can quote a different number.
- Tax scope. The result is a component estimate; withholding, credits, filing status, and state/local rules can change the final liability.
The formulas and assumptions above still govern the number. The worksheet makes the estimate auditable; it does not make it a lender quote, tax return, or personalized advice.
Before you use a quote
Why your bank, lender, or provider’s number may differ
A tax authority’s number can differ because withholding, credits, filing status, state and local rules, and the final tax return are not all captured by a single calculator.
What changes the quote
- Withholding versus liability. A paycheck estimate is not a tax return; credits and other income change the final number.
- Filing status and dependents. These change brackets, deductions, and credits.
- State and local rules. Local tax, reciprocity, and surtaxes are not universal.
- Timing. Estimated payments, penalties, and refundable credits depend on the full year.
How to compare offers
- Compare the APR and total cost, not only the monthly payment.
- Ask for a written quote or Loan Estimate with all fees itemized.
- Use the same loan amount, term, date, and assumptions for every offer.
- Check what is excluded: taxes, insurance, closing costs, maintenance, or provider fees.
- Keep an emergency reserve; the lowest payment is not always the safest choice.
Reference: CFPB Loan Estimate explainer.
Part of a decision center
Tax & Paycheck Center
See the companion tools, decision guides, and patterns that go with this calculator.
Go deeper